By the Numbers
New-home inventory fell to its lowest level since December.
The month-over-month bump in contract signings was still below the pace of last August.
While a decline in closed sales is largely seasonal, the fact that pending sales fell for the fifth month in a row suggests something besides mere seasonality is at work, GAMLS said.
Since the Hispanic Wealth Project’s founding in 2014, Hispanic household wealth has more than tripled across the U.S.
In Atlanta, buyers who wait until the last week of September to buy stand to see 14.6% more active listings.
At the same time, the median-sales price rose again, as months’ supply of homes for sale hit a 10-year high.
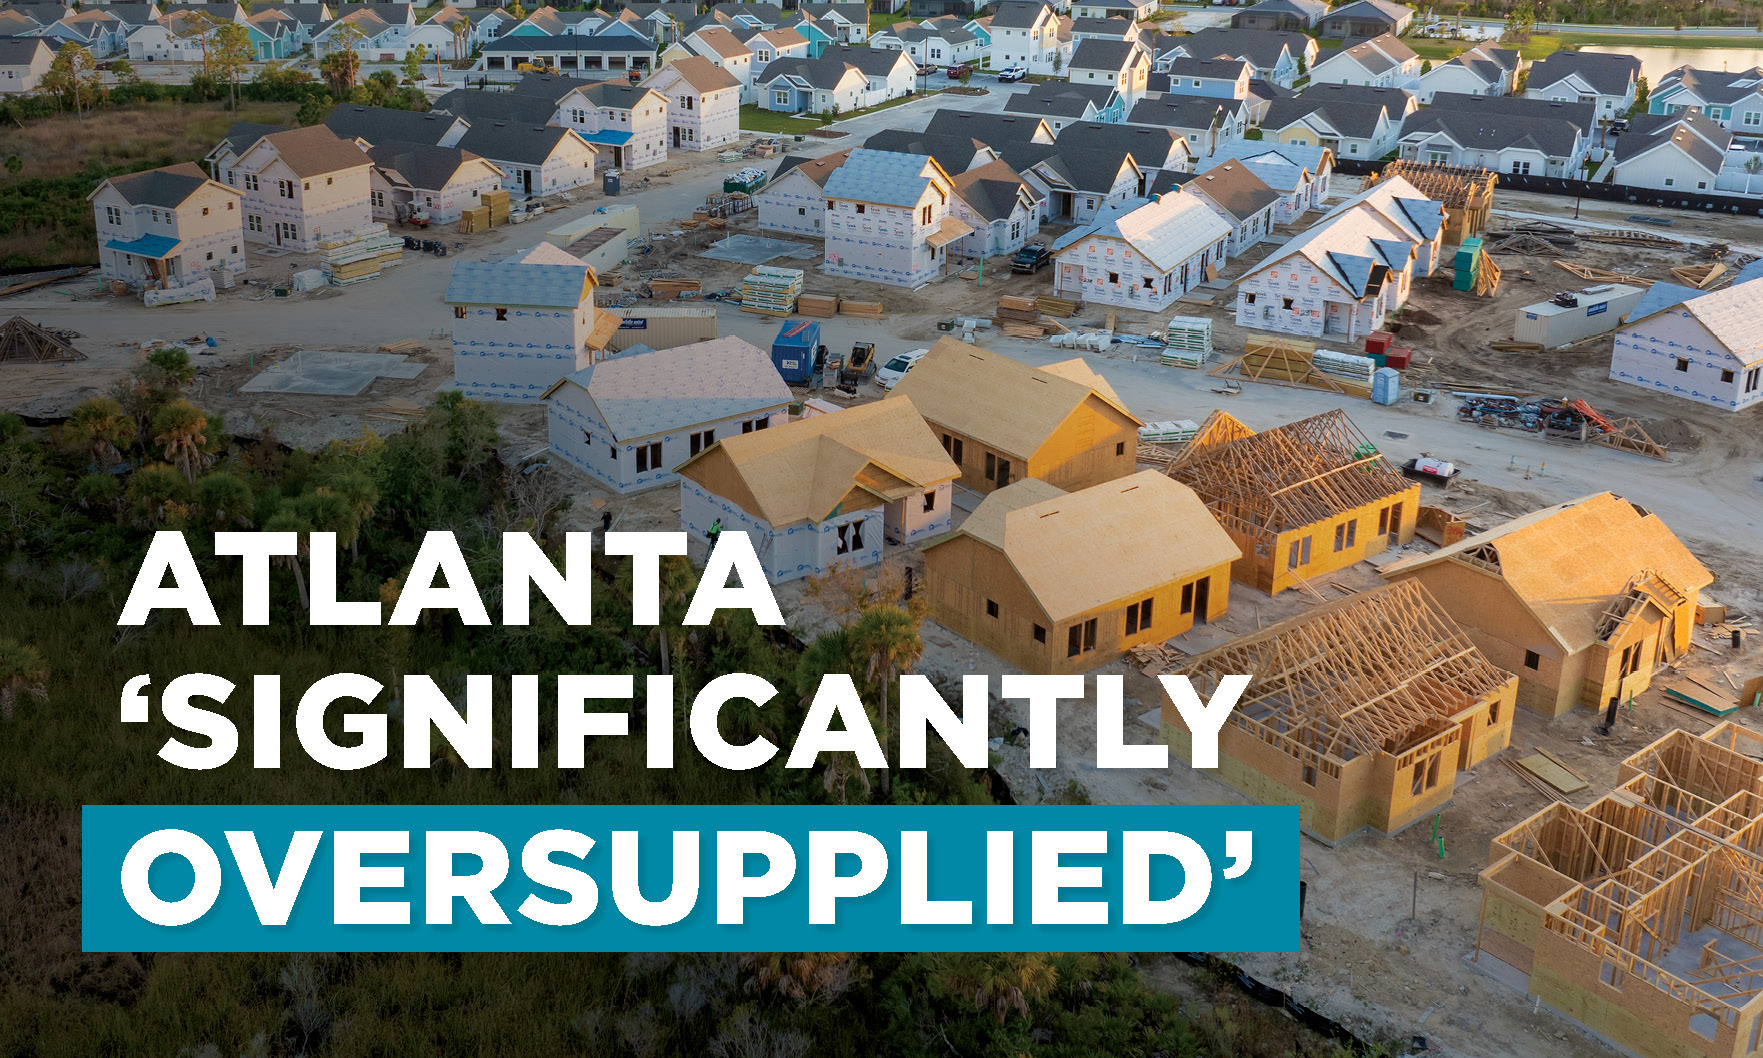
Nationally, the United States is “appropriately supplied” with lots ready for new homes.
The increase in purchase activity offset a decrease in refinancings.
The pace of home-price growth rose nationally but with significant regional differences.
Nationally, home sales in the 46 metro areas surveyed by REMAX rose 2.5% year over year and slipped 5.7% month over month.
Active buyers are looking for more expensive homes, while price-constrained buyers are looking at fewer homes altogether.
Of the 50 metro areas surveyed by NAR, several stood out for year-over-year gains in contract signings.
The move was an improvement over July, but sentiment still remained in negative territory.
Looking ahead, Cotality expects the median price of a home to increase 1.5% through June 2027.
Active listings are providing more choice, while pending sales slid for the fourth month in a row.
Nationally, home-price growth topped 1% for the first time in 2026.